Accounting
GoBD Audit Explained: Requirements for Audit-Ready Digital Bookkeeping in Germany and Beyond

Head of Product - CPO, AODocs · Aug 15, 2026 · Updated Oct 16, 2026

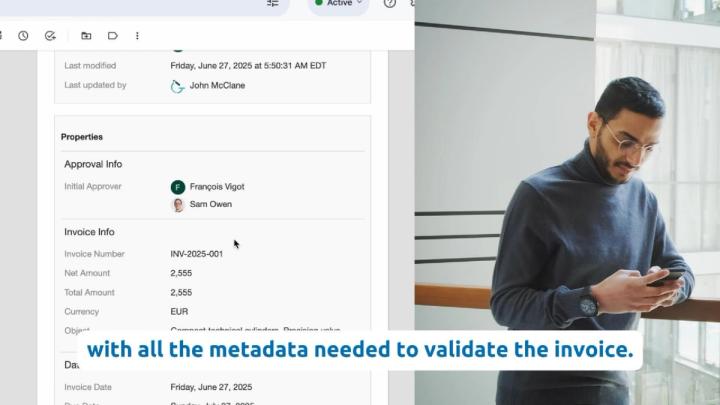
Germany's e-invoicing rules reinforce the need to preserve original structured invoice data. A separate human-readable version is not always required; it must also be retained if it contains additional or different tax-relevant information. GoBD supports traceability, controlled corrections, and access to tax-relevant records.
Organizations subject to German bookkeeping and tax-record obligations must assess the applicable GoBD requirements. GoBD is administrative guidance from the Federal Ministry of Finance on how those obligations apply to electronic records and data access. The consequences of deficient records depend on the facts and applicable law.
The BMF amendments of July 14, 2025 clarify electronic invoice retention. Preserve the structured data. Retain an additional human-readable component when it contains extra or different tax-relevant information. Assess accessibility, traceability and the applicable recordkeeping process separately from other jurisdictions' rules.
Understanding GoBD
The GoBD sets out principles for keeping and retaining electronic books, records and documents and for tax-authority data access. The BMF guidance explains bookkeeping and recordkeeping obligations, including those under section 146 of the German Fiscal Code. The scope depends on the records and obligations of the business.
The November 2019 guidance has been amended, including in March 2024 and July 2025. Use the applicable amended text when assessing a process.
Key principles include:
- Traceability and verifiability of all entries and records
- Immutability so later corrections preserve the original entry and remain traceable
- Timely and systematic recording: section 146 AO requires timely, orderly records and daily recording of cash receipts and payments. Assess non-cash recording procedures against the applicable GoBD requirements.
- Applicable retention periods: invoices generally have an eight-year retention period under section 14b UStG. Check record-specific rules and circumstances that extend retention.
- Documentation of IT systems and processes
- Ensuring auditor access to records when required; tax authorities may request tax relevant documents in digital form for a digital audit
Company size alone does not determine the relevant recordkeeping controls. Identify the bookkeeping and retention obligations that apply to the entity and the records being assessed.
The 2025 update places special emphasis on e-invoice archiving: preserve the original structured data. A human-readable component also requires retention when it contains additional or different tax-relevant information. Records must remain accessible and changes traceable. GoBD covers tax-relevant records in both digital and paper workflows.
Common Pitfalls in GoBD Compliance for Tax Relevant Data
Organizations often stumble when implementing GoBD, and the 2025 update introduces new challenges and risks tied to the e-invoicing mandate. Common pitfalls now include:
- Incorrect e-invoice archiving and missing documentation requirements for digital records and tax-relevant documents across systems, such as storing only the human-readable PDF or print version but not the original structured XML data required under the amended rules.
- Storing records in formats that can't be reproduced exactly, compromising authenticity.
- Failing to maintain version history or audit logs, hindering traceability.
- Inadequate retention controls: applying one period to all records or deleting records while a longer retention obligation applies.
- Scattered systems with no centralized oversight or governance for audit readiness.
E-invoice retention requires preserving the machine-readable source data. Retain related human-friendly formats when they contain additional or different tax-relevant information. Preserve accessibility and traceability throughout the applicable retention period.
These gaps can make tax-relevant records harder to reconstruct and review. Document the process and test whether the retained records remain accessible and understandable.
Building a Strong GoBD Compliance Framework
A GoBD assessment should examine the technical and organizational controls used for tax-relevant records. The guidance does not prescribe one archive technology or a single centralized system. Review how the process provides:
- Protection against untraceable changes, using the technical and organizational controls appropriate to the records
- Defined record ownership and consistent handling across the systems involved
- Detailed audit trails, retaining a traceable history of relevant entries and corrections
- Retention procedures mapped to applicable schedules, with any automated rules tested
- Secure, role-based access controls, balancing security with usability
These steps help ensure records remain reliable, accessible, and defensible over time, while supporting legal requirements and helping maintain records suitable for audit review.
Why GoBD Is Worth Knowing Beyond Germany
GoBD is relevant to obligations under German tax law. Organizations working across jurisdictions should assess each jurisdiction's recordkeeping rules separately; similar principles do not make the legal requirements interchangeable.
GoBD offers a concrete example of how strict digital recordkeeping principles may be applied in a regulatory context, especially regarding immutability, auditability, and long-term retention. Organizations subject to German tax-record obligations must assess the applicable GoBD requirements. Others may use its principles as context without treating it as law in their jurisdiction.
While tax-record retention requirements differ by jurisdiction and record type, the details vary significantly by country. In that regard, while not a standard adopted elsewhere, GoBD can serve as a reference point.
Assessing AODocs Compliance Archive for GoBD-related controls
AODocs' Compliance Archive materials describe financial-record controls. They do not establish that a particular deployment meets GoBD. Assess the configured capabilities and supporting process evidence against the requirements that apply:
- Protection of retained records and traceable corrections, demonstrated in the configured archive
- Retention rules mapped to a reviewed schedule for the relevant record types
- Access to the records and reports needed to review the archive process
- Configured integration with Google Workspace, subject to tested retention, retrieval, and access controls
Where extraction is used, verify the retained source record, extracted fields and correction process. Process design and documentation remain necessary.
Organizations must assess archive configuration, procedures, and documentation against their applicable GoBD obligations. A software purchase does not establish compliance, and businesses remain responsible even when records are managed with software or with support from a tax advisor.
Learn More
Frequently asked questions
Is a PDF enough to archive an electronic invoice under German GoBD rules?
A PDF alone is not enough when the invoice includes a structured electronic component that must be preserved. Germany's Federal Ministry of Finance says the structured part must remain intact in its original form. Under the current GoBD text, an additional human-readable component is required when it contains extra or different information relevant to taxation.
How long must electronic invoices be retained in Germany?
Under section 14b(1) of Germany's VAT Act, incoming and outgoing invoices generally must be retained for eight years. Other record categories, applicable tax rules, and circumstances can require different treatment. Use a reviewed schedule by record type rather than applying one period to every digital document.
Can a bookkeeping error be corrected without breaching GoBD immutability?
A correction can be made, but it must not conceal the original entry or make the timing and nature of the change unclear. GoBD immutability protects the evidential history rather than banning documented corrections. Preserve the original information and the correction trail within the documented bookkeeping process.
What should GoBD process documentation explain?
GoBD process documentation should explain how tax-relevant records are created, received, processed, stored, and made accessible. Its detail depends on the business and the systems used. Keep the description aligned with actual operations and preserve relevant historical versions so an auditor can understand the process used during the retention period.